The payments industry is witnessing one of its most significant transformations since the introduction of contactless payments. The lines between traditional credit cards and Buy Now, Pay Later (BNPL) solutions are rapidly blurring, creating a new generation of payment products that combine the flexibility of instalment financing with the acceptance and reliability of credit cards.
Consumers today no longer view credit as a one-size-fits-all product. They expect flexibility, transparency, and control over how they pay for purchases. This shift in consumer behavior has prompted banks and card issuers to rethink traditional revolving credit models by embedding BNPL capabilities directly into their existing credit card offerings.
The convergence of credit cards and BNPL is not merely a product enhancement—it represents a fundamental evolution in consumer lending and the future of digital payments.
Changing Consumer Expectations
Over the last decade, digital-native consumers have become accustomed to seamless online experiences. Whether ordering food, booking travel, or shopping online, customers expect payment options that are instant, transparent, and personalized.
Traditional credit cards offer convenience but often come with revolving balances, complex interest calculations, and minimum payment structures that many younger consumers find difficult to manage. In contrast, BNPL introduced a simpler value proposition:
- Fixed instalments
- Transparent repayment schedules
- Low or zero interest for eligible purchases
- Instant approval at checkout
- Better budgeting and expense visibility
These benefits have made BNPL particularly attractive to Millennials and Gen Z consumers, many of whom are cautious about accumulating long-term revolving debt.
Rather than losing customers to standalone BNPL providers, banks are now bringing these capabilities into their own card ecosystems.
Commercial Cards: Bringing BNPL Flexibility to Business Spending
While Buy Now, Pay Later (BNPL) has primarily been associated with retail consumers, its underlying concept is rapidly finding its way into the commercial card ecosystem. Businesses today are seeking the same payment flexibility that consumers have come to expect, with greater control over cash flow, simplified financing, and frictionless purchasing experiences.
The Evolution of Commercial Cards
Traditional commercial cards have long been used for corporate travel and entertainment expenses, procurement and supplier payments, fleet management, virtual cards for online purchases, and working capital optimization.
However, modern businesses are demanding more than payment convenience. They increasingly expect financing options to be embedded directly into the payment experience.
BNPL Meets Commercial Cards
Leading card issuers are integrating instalment financing into commercial credit cards, allowing businesses to convert large purchases into fixed monthly instalments, preserve working capital without arranging separate loans, improve budgeting through predictable repayment schedules, and finance capital expenditure without lengthy approval processes.
For example, instead of paying ₹20 lakh upfront for manufacturing equipment, a company can instantly convert the transaction into a 12-month repayment plan directly from its commercial card portal.
This effectively transforms a commercial card into a flexible short-term financing instrument.
Embedded Finance for Enterprises: Financing at the Point of Business
Embedded finance is extending beyond consumer applications into enterprise ecosystems. Instead of applying for loans through banks, businesses can now access financing directly within the software platforms they already use.
This represents one of the most significant shifts in commercial payments.
What Is Embedded Finance?
Embedded finance enables financial services—such as lending, payments, insurance, and banking—to be integrated directly into non-financial platforms.
Examples include:
- ERP systems
- Procurement platforms
- B2B marketplaces
- Accounting software
- Supply chain management solutions
- E-commerce platforms
The financing becomes almost invisible, delivered precisely when businesses need it.
How It Connects with Credit Cards and BNPL
Commercial credit cards increasingly serve as the payment rail, while embedded finance provides the financing layer.
A typical workflow might look like this:
- A business orders inventory through its procurement platform.
- At checkout, the platform presents financing options.
- The purchase is charged to a commercial card.
- The issuer instantly converts the transaction into structured instalments.
- Repayments are managed automatically through the enterprise finance platform.
The financing decision occurs in seconds, without requiring businesses to leave their workflow.
Digital-First Customer Experiences
Customers expect financing decisions within seconds. Mobile banking applications now allow users to activate instalment plans, track repayments, modify schedules, and receive personalized financing recommendations—all without contacting customer service.
Opportunities for the Payments Ecosystem
The convergence of credit cards and BNPL creates value across the ecosystem.
For issuers, it offers opportunities to increase card transaction volumes, improve customer retention, generate additional fee-based revenue, enhance digital engagement, and attract younger customer segments.
Merchants benefit through higher average order values, improved checkout conversion rates, reduced cart abandonment, and increased customer loyalty.
Consumers gain greater financial flexibility, transparent repayment structures, better budgeting capabilities, and continued access to the broad acceptance of traditional credit cards.
This alignment of incentives explains why hybrid card-BNPL products are rapidly gaining momentum worldwide.
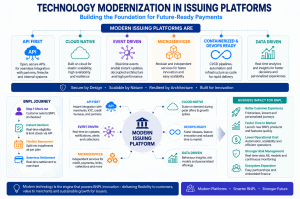
Technology Modernization
Many financial institutions continue to operate on decades-old card processing platforms. Integrating flexible instalment capabilities without disrupting existing payment infrastructure requires significant investment in modernization and system integration.
Emerging trend – Payment Orchestration
Payment orchestration is emerging as a key capability for BNPL providers, with smart payment routing offering the highest ROI. It enables cost optimization, supports multi-country expansion, and allows for dynamic payment method selection based on transaction requirements. Payment orchestration also enables intelligent failover during outages, helping maintain payment continuity, while supporting embedded BNPL selection as part of the payment experience. Here are some use cases:
1. AI-Powered Real-Time Credit Decisioning (Most Common Use Case)
Business Challenge
Traditional credit scoring often rejects customers with limited credit history, including young professionals, gig workers, and first-time borrowers.
AI Solution
AI evaluates hundreds of data points within seconds, including transaction history, bank account cash flow, salary patterns, spending behavior, device information, repayment history, and alternative credit signals.
2. AI-Based Fraud Detection & Synthetic Identity Detection
Business Challenge
BNPL providers are frequent targets of fake identities, account takeover, multiple applications, deepfake KYC, and stolen credentials.
AI Solution
AI continuously analyses device fingerprint, IP location, typing behaviour, face matching, transaction velocity, merchant patterns, and historical fraud networks.
Business Benefits
AI helps reduce fraud losses, lower false positives, and enable real-time fraud prevention.
Conclusion
The convergence of credit cards and BNPL marks a pivotal shift in the evolution of consumer finance. Rather than replacing traditional credit cards, BNPL is reshaping them into more adaptable and customer-centric payment instruments.
As consumer expectations continue to evolve, issuers that successfully integrate instalment financing into their card portfolios will be better positioned to strengthen customer loyalty, unlock new revenue streams, and remain competitive in an increasingly digital payments landscape.
The future belongs not to choosing between credit cards and BNPL, but to creating seamless payment experiences where both models work together—offering consumers the freedom to pay in the way that best fits their financial lives.